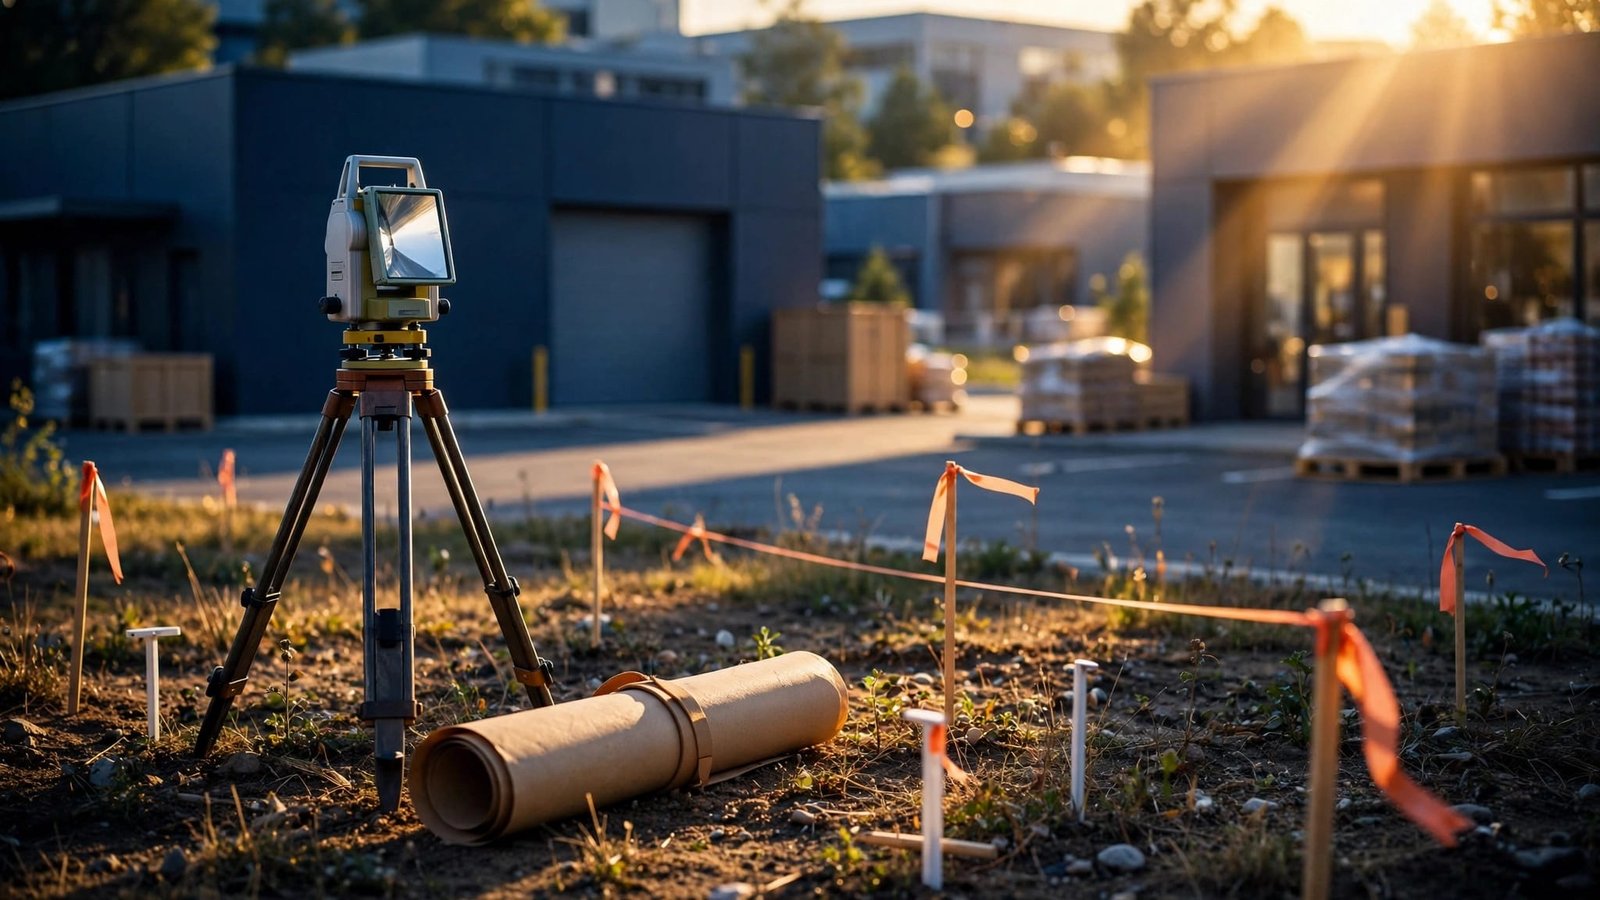
A missed easement or boundary conflict can delay a commercial loan closing when your deposits, payroll, and project schedule are already set. A current commercial property survey gives your lender, title insurer, and legal team a shared picture of what exists on the site before money changes hands.
For an owner acquiring commercial real estate, the survey is more than a map. A pre-acquisition survey is a transaction-focused scope, not a universally defined product. It compares the legal description with visible site conditions, helping identify property boundaries, access problems, utility routes, easements, encroachments, and improvements records may not reveal. It isn’t a property-condition inspection or a guarantee of loan approval.
The right scope, ordered early, keeps a correctable issue from becoming a closing-day surprise.
Requirements vary by lender, title insurer, property type, transaction structure, and jurisdiction. Borrowers should confirm the scope with the lender, title company, licensed surveyor, and qualified legal counsel. This article provides general information, not legal advice.
This post may contain affiliate links. If you make a purchase through these links, I may earn a small commission at no extra cost to you.
Key Takeaways
- A current commercial property survey compares the legal description with visible site conditions and can identify boundary conflicts, easements, access problems, utility evidence, encroachments, and other issues before closing.
- An ALTA/NSPS Land Title Survey is commonly requested for sizeable commercial transactions, but the lender, title insurer, property type, transaction structure, and jurisdiction determine the required scope.
- Order the survey early with the current title commitment, recorded exceptions, site plans, and written lender instructions. Allow roughly two to four weeks for a typical assignment, with additional time for complex sites, access limits, or revisions.
- A survey doesn’t replace a title review, property-condition assessment, environmental review, zoning determination, flood determination, or legal advice. Coordinate findings with the surveyor, lender, title company, and qualified counsel before closing.
- Retain the final signed and sealed survey and related approvals in the property file to support future refinancing, construction planning, tenant improvements, expansion, and resale.
Know what makes a survey necessary at closing
No single federal rule requires every commercial buyer to obtain the same survey. However, lenders and title companies commonly make one a condition of closing because the property secures the loan.
The loan agreement, lender’s underwriting instructions, property type, planned use, loan structure, and jurisdiction determine the required scope. A simple refinance of an established office building may need less field work than a ground-up construction loan on a multi-parcel site.
Legal rules and lender conditions are different
State law governs who may perform a land survey and how surveying practice is regulated. Local zoning laws, setback rules, subdivision requirements, and floodplain regulations may affect the buyer’s due diligence.
Yet, the demand for an ALTA/NSPS survey usually comes from the lender and title insurer. They need reliable information to assess risks affecting collateral, legal access, and insurability. The survey may inform property valuation and the title-insurance decision, but it doesn’t determine value or cure a title defect.
Review the current title commitment before ordering. Send its listed exceptions and recorded documents to the surveyor, so the required items can be plotted.
Why title insurance alone is not enough
A title commitment focuses on recorded rights and documents. It may not show a neighbor’s fence crossing the line, an access drive used without a recorded easement, or a building addition sitting in a setback. Reviewing recorded documents and visible conditions together helps identify easements and encroachments.
A pre-acquisition survey compares the legal description with visible conditions on the ground, helping confirm property boundaries as part of broader due diligence. It can support review of access, zoning, and recorded rights, but it doesn’t establish legal compliance. Qualified counsel should address legal conclusions.
That comparison helps the title company, not the surveyor or borrower, decide whether an exception or endorsement is available and whether standard survey exceptions can be removed or limited in the final policy.
A survey issue found before closing can often be cured, insured over, or negotiated with the title company. The same issue found after closing can limit the property’s use and resale value.
Commercial Survey Standards Lenders Recognize
For many sizeable U.S. commercial transactions, an ALTA survey, formally an ALTA/NSPS Land Title Survey, is commonly requested by lenders and title insurers. A commercial property survey prepared to this standard isn’t automatic for every deal.
Verify the applicable edition and effective date against the article’s publication date and official NSPS source. The 2026 ALTA/NSPS Standards took effect on February 23, 2026.
These national minimum standards create a consistent framework. Still, they do not replace state surveying requirements or the lender’s written instructions.
A licensed commercial surveyor signs and seals the final survey. The surveyor certifies it to the specifically named parties required by the transaction. That certification isn’t a warranty of title, zoning approval, flood-insurance eligibility, or loan approval.
What the base ALTA/NSPS survey shows
The base ALTA survey starts with the legal boundary. It then locates visible improvements and compares them with the title evidence and site plan supplied for the transaction.
Depending on the site, the completed survey can identify:
- Boundary lines, corners, monuments, and acreage.
- Buildings, parking areas, drives, sidewalks, fences, signs, and visible improvements.
- Recorded easements, rights-of-way, access points, and utility evidence.
- Visible evidence of occupation or use along the property’s perimeter.
- Potential encroachments, such as a wall, overhang, paving area, or fence crossing a line.
For complex or dense sites, laser scanning may support field collection. It isn’t an ALTA/NSPS requirement and doesn’t replace required research, fieldwork, certification, or lender review.
The 2026 update places more emphasis on perimeter occupation and utility evidence. It also introduced Table A Item 20, an optional encroachment summary table that can make review easier for the closing team. A summary of the 2026 revisions explains several changes affecting current transactions.
Table A items shape the final scope
Table A contains optional items beyond the base standard. The lender, title company, surveyor, and counsel should agree in writing on the selections and any lender-specific instructions.
Common requests cover zoning setbacks, observed utilities, parking counts, building heights, flood-zone information, and evidence of access. These items can be especially important for land development parcels. Don’t assume a prior owner’s survey includes the items required for your loan.
Photo by Pavel Danilyuk
Match the survey type to the property plan
An ALTA/NSPS survey is often the closing standard, but it may not answer every question tied to your intended use. A pre-acquisition survey describes the buyer’s due-diligence purpose, not a single survey product. Depending on the transaction, its deliverables may include ALTA/NSPS work, boundary or topographic mapping, zoning research, or other specialized work.
Boundary and topographic surveys solve different problems
A boundary survey establishes or retraces property lines and monuments. It may be enough for a lower-risk transaction where the lender doesn’t require an ALTA/NSPS product.
A topographic survey records elevations, contours, drainage, vegetation, and existing site features. Architects and civil engineers use it to design grading, drainage, utilities, parking, and building placement. It’s especially important before land development because a site can look level while still creating expensive drainage or retaining-wall work. Neither product should automatically replace the lender’s required ALTA/NSPS survey.
Construction teams may also need construction staking after plans receive approval. During construction, this construction staking locates approved design elements in the field, such as building corners and utility lines. It also helps crews verify grading points before installation. It isn’t evidence that the closing survey is current. An as-built survey documents the improvements’ final installed locations after construction.
Building and lease due diligence need another lens
A land survey doesn’t replace a property condition assessment, environmental review, or inspection of roof, HVAC, electrical, and structural systems. A separate building survey focuses on the asset itself, not its legal boundaries.
That review examines physical condition and structural condition, rather than legal boundaries. Its evaluation of structural condition should come from the building survey or inspection, not an ALTA/NSPS boundary product.
For leased commercial space, a dilapidation assessment evaluates defects, wear, and reinstatement obligations at lease end or during negotiations. In UK practice, RICS surveyors may prepare a dilapidation assessment for lease negotiations and future claims. This isn’t a standard U.S. commercial loan requirement. In the U.S., a condition report records defects and wear at lease start. It differs from a dilapidation assessment used for lease-end obligations. Photographs and written records can still protect both landlord and tenant.
Order the survey before the closing calendar tightens
A typical commercial ALTA/NSP assignment may take roughly two to four weeks. Multiple parcels, uncertain records, difficult access, tenant restrictions, complex Table A requests, weather, or revision cycles may add time.
Start after receiving the current title commitment, rather than waiting for final closing documents. A pre-acquisition survey can begin during early due diligence. These four moves keep the work moving:
- Send the complete title package. Give the commercial surveyor the legal description, recorded exceptions, prior surveys, plats, an available site plan, and other supporting plans.
- Confirm the lender’s written requirements. Ask whether it requires a current ALTA survey, an update, or a survey affidavit. Confirm any specific Table A items, zoning support, flood documentation, or certification requirements. An affidavit or update may be lender- or title-company-specific. Neither is interchangeable with a new survey unless those parties approve it in writing.
- Give the survey team site access. Locked gates, tenant restrictions, active construction, limited daylight, and weather can slow fieldwork. Tell the surveyor about access limits at the start. If later work requires construction staking, treat it as a separate service from closing documentation.
- Review the draft with the deal team. Make this the final pre-review checkpoint. Compare the draft with the title materials, purchase agreement, appraisal, intended use, and lender checklist. Obtain corrections, then secure the final signed and sealed certification before closing.
A surveyor can’t fix a title defect. Early review gives the seller time to obtain a release, relocate an improvement, grant an easement, or negotiate a title endorsement. Obtain written approval from the lender and title company for any affidavit, update, or exception treatment. Seek legal advice on defects, easements, access, or zoning issues.
Budget for survey work without putting operations at risk
As an illustrative planning range, survey work may run from roughly $2,000 to $10,000 or more. This range isn’t a quote or guarantee.
Pricing depends on acreage, parcel count, urban density, record research, boundary uncertainty, terrain, flood-related work, utility research, and Table A items. Rush service, limited site access, and revision requests can also increase the fee.
Ask for an itemized proposal before authorizing the work. It should identify fieldwork, research, drafting, revisions, certification, travel, and extra services. Confirm the expected delivery date and who bears payment responsibility.
Survey fees are separate transaction costs in a commercial real estate loan. Budget separately for title, zoning, flood, legal, and inspection expenses.
The expense can land at an awkward time. A contractor may be waiting for a project milestone while paying crews and materials. A retail owner may be placing holiday orders. A healthcare practice may be waiting on insurance reimbursements.
Keep operating capital separate from property equity
Maintain a documented operating-cash reserve for timing gaps during the transaction. Don’t use undisclosed new obligations to create the appearance of additional cash equity.
Your senior lender may require disclosure of every new obligation before closing. Keep working capital needs separate from the property financing structure, and confirm any funding decision with your lender and financial advisers.
Prepare for the survey findings that delay deals
Most commercial survey problems are manageable. The risk grows when the team treats the first draft as a formality. Use a pre-acquisition survey to review easements and encroachments with the surveyor, title company, lender, and counsel.
| Survey finding | Why it matters | Action and required approval |
|---|---|---|
| Fence, drive, or building encroachment | It can affect property boundaries, use, or neighbor rights | Ask the surveyor to verify the location and issue a survey correction if needed. If confirmed, both affected property owners must approve a release, boundary agreement, or relocation. The title company and lender must approve any title endorsement. |
| Easement through a parking or building area | It may restrict expansion, access, or site operations | Have counsel review the recorded right. The property owner and easement holder must approve any release or use agreement. The title company and lender must approve related coverage. |
| Missing legal access | The property may lack dependable ingress and egress | Confirm the record with the title company and counsel. The affected owner must grant an access easement, and the title company and lender must approve it. If no solution exists, the buyer, seller, and lender must approve a transaction revision. |
| Setback or zoning conflict | Planned use or expansion may be blocked | Ask the surveyor for a survey correction if location data is wrong. Otherwise, the local zoning authority must confirm the intended use. The buyer and seller may negotiate a price adjustment, subject to lender approval. |
| Flood-zone concern | Insurance, elevation data, and lender conditions may change | Confirm current FEMA and local maps. Obtain required flood documentation, then satisfy the lender’s and insurer’s documentation and coverage conditions. |
Note: Construction staking doesn’t cure a boundary, access, or title problem. Schedule it only after approved plans and the relevant rights are confirmed.
Flood plain review deserves early attention, although floodplain is often the standard technical spelling. A lender may separately order a flood determination and insurance review. Survey location and elevation information supports that work, but it isn’t an official flood determination. An elevation certificate isn’t automatic in every ALTA/NSPS survey; lenders, insurers, FEMA-related processes, and local authorities may require it.
Survey findings don’t replace a building inspection, environmental review, or property condition assessment. Survey facts can inform zoning, access, flood, and setback review. They can’t certify regulatory compliance or legal compliance. Ask the appropriate authority and qualified counsel to assess those issues.
A material survey issue may affect the lender’s appraisal or property valuation analysis, but the surveyor doesn’t establish market value.
Before closing, the borrower should coordinate with the lender, title company, surveyor, and legal counsel:
- Confirm the legal description and all parcels.
- Review every title exception.
- Verify legal access and parking.
- Check easements and visible encroachments.
- Compare zoning and setbacks with the intended use.
- Confirm flood and elevation deliverables.
- Obtain the final signed and sealed survey.
- Secure written lender and title company approval for outstanding items.
For a business with $10,000 or more in monthly revenue, temporary financing may keep routine expenses moving. It can help while attorneys and title professionals resolve an issue. Still, disclose any new financing to the commercial lender.
Use the closing process to strengthen future financing
A clean survey file does more than support one purchase. It creates a reliable property record for refinancing, tenant improvements, expansion, construction planning, and resale.
Retain the final survey, certification, title materials, easement agreements, zoning confirmations, flood documents, and approved revisions in the property file. Future construction may require a separate construction staking engagement based on approved plans. Staking isn’t part of the closing survey and doesn’t replace an updated survey.
Organized records can reduce future diligence friction, but they don’t guarantee refinancing, valuation, tenant approval, permitting, or loan approval. Owners should also maintain accurate business records, and Business credit-building programs may support that discipline as the company grows.
Use future capital for a defined purpose with a clear repayment source. For established companies, premium funding options may support planned expansion, but new debt shouldn’t cover preventable survey delays or incomplete property records.
Frequently Asked Questions
Is a commercial property survey required for every commercial loan?
No single federal rule requires the same survey for every commercial transaction. Lenders and title companies commonly require a current survey as a closing condition, with the scope based on the property, loan structure, intended use, and jurisdiction.
What is an ALTA/NSPS Land Title Survey?
An ALTA/NSPS survey is a standardized survey commonly used in sizeable U.S. commercial transactions. It typically addresses boundaries, visible improvements, easements, access, utility evidence, and potential encroachments, along with any agreed optional Table A items.
How early should a borrower order the survey?
Order the survey after receiving the current title commitment and before the closing calendar becomes tight. A typical assignment may take roughly two to four weeks, but multiple parcels, difficult access, complex requirements, weather, and revisions can extend the schedule.
Does a survey replace a property inspection or title review?
No. A survey focuses on boundaries, recorded rights, visible conditions, and related site information, while inspections address building condition and title review addresses recorded ownership interests and exceptions. Zoning, environmental, flood, and legal questions may require separate professionals and documentation.
What happens if the survey finds an encroachment or missing access?
The closing team should confirm the finding and determine whether it can be corrected, released, insured over, or otherwise negotiated. The title company and lender must approve any related endorsement or exception treatment, while qualified counsel should address legal rights and agreements.
Final Thoughts
The survey protects the deal by testing title records against the physical site. Order the appropriate survey early, compare it with the title commitment and intended use, and resolve or insure over problems before closing.
The strongest outcome is a property file with clear boundaries, documented access, known easements, and lender and title-company approval. Requirements vary, so confirm the final scope with the lender, title company, surveyor, and qualified legal counsel. That preparation helps you close with confidence and keep operating cash focused on the business.